
What Does Refinancing a Car Mean? A Simple Guide
November 6, 2026


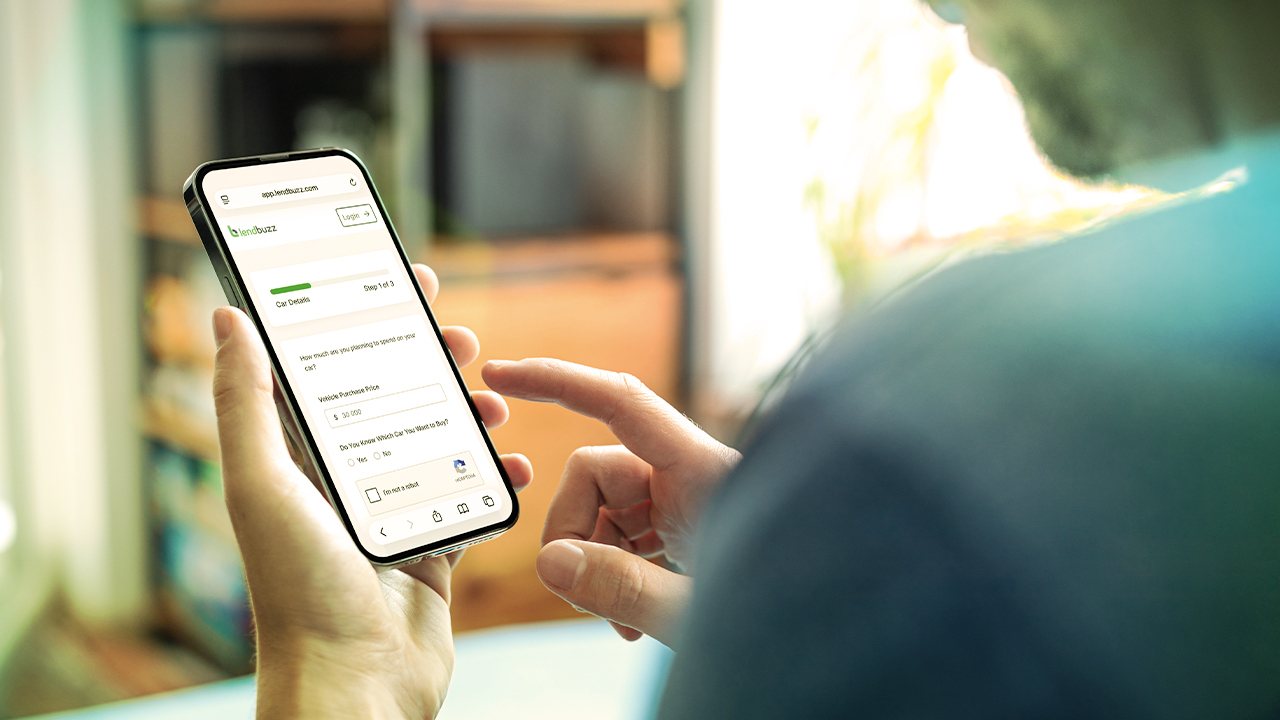
The payment you agreed to when you bought your car was based on your situation that day. Your credit history at the time, the rate the dealership could find, and whatever you could put down.
Months or years later, almost none of that’s still true, but the payment hasn’t moved.
That gap is the whole reason refinancing exists.
So what does refinancing a car mean in practice? It means replacing the loan you have with a different one, usually from a different lender, on terms that fit where you are now rather than where you were then.
You keep the same car. Only the loan changes.
TL;DR
- Refinancing a car means taking out a new auto loan to pay off your current one, with new terms and usually a new lender. The car itself doesn’t change hands.
- People do it to lower their interest rate, reduce the monthly payment, pay the loan off sooner, or get out of a loan they took in a hurry at the dealership.
- The most common trade-off is stretching the loan longer: the monthly payment drops, and you may pay more in total interest by the end.
- It’s worth checking if your credit has improved, rates have moved, or your original loan was arranged quickly without shopping around.
What does refinancing a car mean?
Refinancing a car means a new lender pays off the balance on your existing auto loan, and you start making payments to that new lender instead, under a new agreement.
Nothing happens to the car. You keep driving it, you keep the keys, and you don’t sell it, trade it, or hand it back.
What changes is the paperwork behind it. The old loan closes, a new one opens, and the lienholder recorded on your title is updated from the old lender to the new one.
The lenders and your state's titling agency handle that last part, not you, though it’s usually why a refinance takes a little time to fully complete even after approval.
The reason people ask what it means to refinance a car is that the word sounds bigger than the event. In practice, it’s closer to switching providers than to buying something.
Same car, same driver, different agreement.
"Refinance a car loan" meaning
So what is refinancing a car loan, specifically? It’s the replacement of one auto loan contract with another. When you refinance, several things can change:
- The interest rate on the balance you still owe
- The length of the loan, meaning how many months remain
- The monthly payment amount
- Which lender you deal with, and how you make payments
- In some cases, who’s on the loan, if you want to add or remove a co-borrower
What doesn’t change is the vehicle, your ownership of it, or the fact that the loan is secured by the car.
Refinance car loan meaning, in one line: a new loan on the same car, to replace the old one.
Pros and cons of refinancing a car
Refinancing is useful in some situations and pointless in others; the difference usually comes down to how much you still owe, how long you have left, and what’s changed in your situation since you signed.
Pros of refinancing a car
A lower interest rate. This is the main reason people refinance. If your credit profile has strengthened since you bought the car, or if you took the first financing offered at the dealership without shopping it, there may be room to improve. Rates in the wider market also move over time.
A lower monthly payment. Spreading the remaining balance over more months reduces what you pay each month, which can help if your budget has tightened. See the cons below before treating this as a straightforward win.
Paying the car off sooner. The reverse also works. Refinancing into a shorter term usually raises the monthly payment but can reduce the total interest you pay and get you to a clear title faster.
A lender you would rather deal with. Service quality, app usability, and how a lender handles a missed payment vary a lot. Refinancing is a way to move.
Changing who is on the loan. If someone co-signed for you and no longer needs to be involved, or circumstances have changed, refinancing is typically how that gets resolved.
Getting out of a rushed decision. Plenty of loans get arranged in a finance office at the end of a long day with one option on the table. Refinancing is the second chance to shop that loan properly.
Cons of refinancing a car
You may pay more overall. A longer term with a lower payment often means more total interest by the end. The monthly number improves and the lifetime cost gets worse. Always compare total cost, not just the payment.
There may be fees. Title transfer, registration, and lien recording fees vary by state, and some original loans carry a prepayment penalty. These can eat into a modest saving.
A credit check is involved. Applying usually means a hard inquiry, which may dip your score slightly and temporarily.
Negative equity complicates things. If you owe more than the car is currently worth, your options narrow, because lenders are limited in how much they’ll lend against the vehicle's value.
Older cars may not qualify. Many lenders set limits on vehicle age and mileage for refinancing. A car several years into its life may fall outside them.
It may not be worth the effort. If you’re close to the end of the loan or the balance is small, the savings available are usually small too.
How to refinance a car?
The process is more administrative than difficult, and most of it happens on your phone.
You start by finding your current payoff amount, the exact figure needed to close the existing loan, which your lender can provide.
Then you gather the basics: your car's year, make, model, mileage, and VIN, plus proof of income and insurance.
From there, you compare offers, looking at the rate, the number of months, and the total cost rather than the monthly payment alone.
Once you choose, the new lender pays off your old loan directly, the lien on your title is updated, and you begin paying the new lender.
Your old loan should show as paid off, which is worth confirming rather than assuming.
For a full walkthrough of each step, see our guide on How to refinance a car loan, and if you’re weighing providers, The best auto refinance companies covers what to compare.
Why use Lendbuzz to refinance your car
Many drivers end up with an expensive car loan not because they were a poor risk, but because they had little or no credit history in the United States when they bought, and a traditional credit score said almost nothing about them.
Lendbuzz was built for exactly that situation. Instead of relying on a credit score alone, Lendbuzz looks at a wider picture, including income and cash flow through your bank account, using its own Artificial Intelligence Risk Analysis score, AIRA®, which it calculates for every application.
If you’ve been paying your car loan reliably and your income is steady, that’s information a traditional score may not reflect.
The application is all-digital and can take as little as five minutes on a phone, so checking where you stand doesn’t mean taking an afternoon off.
Get started with refinancing your car now
If your situation has changed since you financed your car, or you took the first offer in front of you at the time, it costs very little to find out what else is available.
See what Lendbuzz can offer on your current auto loan and compare it against what you’re paying today.
Key takeaways
Refinancing a car means replacing your existing auto loan with a new one, usually from a new lender, while keeping the same vehicle.
The rate, term, monthly payment, and lender can all change. The car and your use of it do not.
Whether it’s worth doing depends on your numbers rather than on the idea.
The strongest cases are a credit profile that’s improved since you bought, a loan arranged quickly at a dealership without comparison, or a term you'd structure differently now.
The thing to watch is total cost: lengthening the loan lowers the monthly payment and often raises what you pay in the end. Check your payoff amount, factor in any fees or prepayment penalties, and compare offers on total cost rather than the monthly figure alone.
FAQs
What is the purpose of refinancing a car?
The purpose is to improve the terms of a loan you already have.
Most people refinance to lower their interest rate or monthly payment, pay the car off faster, switch lenders, or add or remove a co-borrower from the agreement.
Is refinancing a car the same as a loan modification?
No. Refinancing replaces your existing loan with an entirely new one, often from a different lender.
A loan modification changes the terms of your current loan with your current lender, and is usually offered in response to financial hardship rather than on request.
How long does the car refinance process take?
Approval decisions can come back quickly, sometimes the same day, though the full process generally takes a few days to a few weeks.
Most of that time is paperwork: paying off the old lender and updating the lienholder recorded on your vehicle's title.
Will refinancing a car always save me money?
No. It depends on your rate, your remaining balance, the new term, and any fees or prepayment penalties involved.
A longer term can lower the monthly payment while increasing total interest paid, so compare the full cost of the loan rather than the payment alone.
Can I refinance my car loan with any lender?
Not necessarily. Lenders set their own requirements covering vehicle age, mileage, remaining balance, loan type, and how long you have held the loan, and not every lender refinances in every state.
Checking eligibility before you apply saves you from unnecessary credit inquiries on loans you were never eligible for.
Will my interest rate always be lower when I refinance a car?
No. Your new rate depends on your current credit profile, the lender, the vehicle, the term you choose, and market conditions at the time.
Refinancing is worth checking rather than assuming, and you’re never obliged to accept an offer you don’t want.
With over a decade in the retail automotive space, Ariana regularly writes on a variety of car dealer and car buyer/borrower-related subjects.